Multi-currency expense tracking: how to manage exchange rates and travel spending
Spending abroad means keeping track of both the local price and what it costs in your home currency. Locking in one practical exchange rate keeps the math simple and your trip budget predictable.
By Pierre Teo · Updated
On this page
- Which exchange rate should you use?
- Why app totals differ from bank statements
- Multi-currency cards like Wise, Revolut, and YouTrip
- Managing cash spending abroad
- Setting up a multi-currency trip in CashJot
- Frequently asked questions
- What exchange rate should I use for a travel budget?
- Why doesn't my trip budget total match my bank statement?
- Should I pay in local currency or my home currency on card machines abroad?
Standing in front of a restaurant menu or a train ticket machine abroad is the worst time to check live currency charts. You don't need four decimal places of exchange-rate precision; you just need to know what dinner costs in your home currency.
Locking in one sensible rate for your whole trip keeps your budget steady and your mental math easy at the counter.
Which exchange rate should you use?#
When you track foreign spending, you have three rates to choose from:
- The mid-market rate: The live baseline rate you see on Google or XE.
- Your card issuer's live rate: The Visa or Mastercard network rate plus your bank's foreign exchange markup, which shifts slightly every day.
- A fixed trip rate: The mid-market rate on the day your trip starts, rounded to a clean number you can do in your head (or padded slightly so your budget stays on the safe side).
For trip tracking, a fixed trip rate works best.
A travel budget is there to help you pace your trip. Answering "can we splurge on this dinner tonight?" is much easier when yesterday's entries aren't shifting around by 0.5% every morning.
Rounding the rate makes mental math effortless at the register (like treating $1 USD as ¥150 JPY, or €1 EUR as $1.50 SGD), and padding it slightly means your actual credit card statement comes in pleasantly under budget.
Why app totals differ from bank statements#
Between the price on the menu and the final charge on your bank statement, a few small markups creep in:
- Network conversion margins: Visa and Mastercard convert foreign charges using daily wholesale rates that sit slightly above the mid-market rate.
- Foreign transaction fees: If your card charges a foreign transaction fee (typically 1% to 3% on US cards, per NerdWallet's card roundup; Singapore banks commonly charge around 3.25%, per DBS's fee schedule), that fee gets tacked onto every swipe.
- Weekend settlement buffers: Charges made over the weekend often use Friday's closing rate or a small weekend buffer until the payment settles on Monday.
- Dynamic Currency Conversion (DCC): When a card machine or ATM asks if you want to pay in your home currency "for convenience", always say no. Visa requires terminals to give you the choice (Visa currency conversion rules). Always pick the local currency. The terminal's built-in conversion rate is set by the merchant's bank and carries steep markups. A peer-reviewed study of DCC pricing found an average markup of 7.6% above card network rates, with some terminals charging up to 12.4% (Gerritsen, Lancee and Rigtering, 2023).
Because of these spreads, a trip budget using one fixed rate and your final card statement will naturally differ by a couple of percent. If you want your app total to match what leaves your bank account, just pad your fixed rate by 2–3% when you set up the trip.
Multi-currency cards like Wise, Revolut, and YouTrip#
Travel cards like Wise, Revolut, and YouTrip hold balances in several currencies at once and deduct straight from your local currency balance when you tap.
You still log purchases the exact same way: enter the local price printed on the receipt, and let your app convert it to your home currency at your fixed trip rate. Even if you converted the money weeks ago inside Wise, seeing the home-currency equivalent on every purchase is what keeps your daily spending on pace.
If your tracker captures Apple Pay taps, check how it handles foreign currencies. CashJot reads the currency Wallet reports for each tap, so a payment charged in yen arrives in yen. Just add the currency to your trip group before you fly: if a tap comes in with a currency the group doesn't have yet, it waits in Captures with a prompt to add it. Without CashJot Plus, every tap appears in Captures; with Plus, taps log automatically. See our Apple Pay capture currency settings for the full setup.
Managing cash spending abroad#
Foreign cash follows the golden rule of cash tracking: log either the ATM withdrawal or the individual purchases, never both.
On a short trip, the easiest option is logging each ATM withdrawal in local currency at your fixed rate, then spending the bills without logging every street snack. If cash is your main way of paying on the trip, skip the ATM withdrawal and log each purchase as you go. Our guide to tracking cash spending covers both setups.
Setting up a multi-currency trip in CashJot#
In CashJot, a trip abroad or a foreign client gets its own Expense Group:
- Create a new Expense Group (like "Tokyo Trip 2026"): tap the group name on the Log tab, then Edit → +.
- In the group's editor, tap Add Currency, pick the local currency (like JPY), and enter your fixed exchange rate against your home currency.
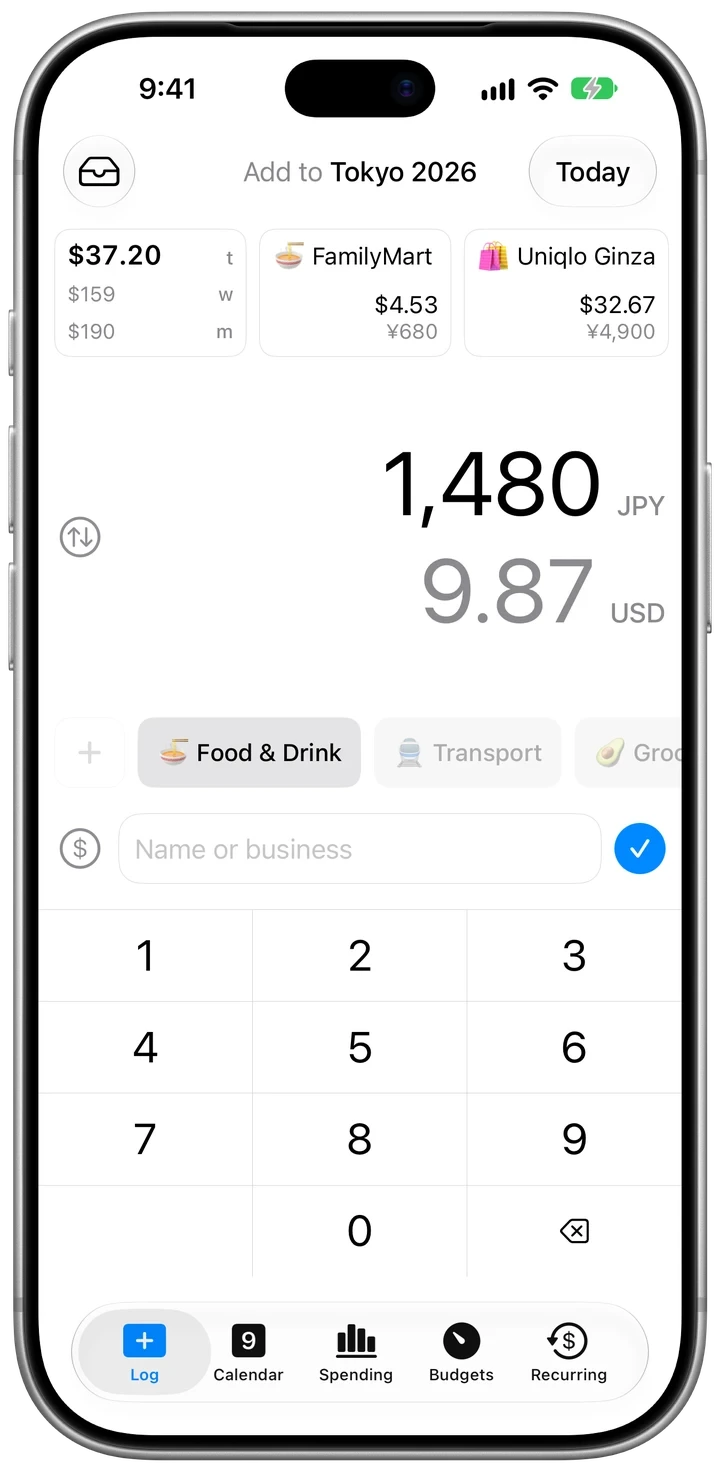
- Log expenses as usual: the circled $ button beside the name field switches currencies, the circled arrows swap which amount you're typing, every entry shows both currencies, and your trip budget totals everything in your home currency.
Your first Expense Group is free; a second group and logging in foreign currencies are part of CashJot Plus.
Our complete travel expense tracking guide walks through setting up trip groups, dated budgets, and archiving old trips once you're home.
Frequently asked questions#
What exchange rate should I use for a travel budget?#
Use one fixed exchange rate set at the start of your trip. Take the mid-market rate on the day you leave, round it to an easy number for mental math, or pad it slightly if you want your budget to stay on the safe side.
Why doesn't my trip budget total match my bank statement?#
Card statements use daily network rates, bank fees, and settlement-date rates, while your travel budget uses one steady rate for the whole trip. Being off by a couple of percent is completely normal.
Should I pay in local currency or my home currency on card machines abroad?#
Always pick local currency. Choosing your home currency triggers Dynamic Currency Conversion (DCC), which lets the merchant's terminal charge its own high exchange-rate markup (averaging 7.6% extra). Paying in local currency lets Visa, Mastercard, or your travel card convert it at a fraction of the cost.
Written by Pierre Teo, maker of CashJot.